---
title: Advantage Credit - Level 1 - Partner Highlight Page
description: "Wilqo delivers a modern solution for lenders wanting to optimize throughput, ensure accuracy, and close more loans, all while providing a transparent and simple process for their borrowers, partners, and staff.
Our cloud-native Production Optimization Platform (POP) breaks the lending process down to discrete tasks at the atomic level for each loan.
We automate every step in the loan manufacturing process, prioritize those activities that need human intervention, and provide actionable insights into where lenders are making (or losing) money across the entire enterprise.
The result: a better experience for everyone + a lower cost to produce a closed loan."
image: https://wilqo.com/hubfs/logo%20for%20linkedin.png
---
[](https://wilqo.com?hsLang=en)
[](http://WILQO.com)
- [Home](https://wilqo.com)
- Our Solution
- [Unified POS+LOS](https://wilqo.com/pos-los)
- [Content Intelligence](https://wilqo.com/content-intelligence)
- [Business Intelligence](https://wilqo.com/business-intelligence)
- [Partners](https://wilqo.com/integration-partner)
- [Team](https://wilqo.com/team)
- [The Wilqo Way](https://wilqo.com/wilqo-way)
- [Videos](https://wilqo.com/videos)
[ Request a Demo ](https://wilqo.com?hsLang=en#contactus)
[ Request a Demo ](https://wilqo.com?hsLang=en#contact-us)
[ Request a Demo ](https://wilqo.com?hsLang=en#contact-us)
- [Home](https://wilqo.com)
- Our Solution
- [Unified POS+LOS](https://wilqo.com/pos-los)
- [Content Intelligence](https://wilqo.com/content-intelligence)
- [Business Intelligence](https://wilqo.com/business-intelligence)
- [Partners](https://wilqo.com/integration-partner)
- [Team](https://wilqo.com/team)
- [The Wilqo Way](https://wilqo.com/wilqo-way)
- [Videos](https://wilqo.com/videos)
[ Request a Demo ](https://wilqo.com?hsLang=en#contact-us)
### The Mortgage Industry is Broken
#### And your LOS is the reason.
#### We have the cure.

## Meet Advantage Partners Solutions
Advantage Partners Solutions is a national leading provider of mortgage and banking solutions, and business credit solutions. We have a proud history of providing superior customer service while leveraging the most advanced credit technologies for leading mortgage companies, banks, and credit unions nationwide. We offer more than just credit reports, Advantage Partners Solutions offers a plethora of credit reporting services such as: credit verification services, tax transcripts, rescore services, undisclosed debt monitoring, automated valuation, flood zone determination, disclosure compliance trended credit data, liens and judgments reports, business credit reports and lead generation. We also offer outside the box services such as Monitoring Advantage, our proprietary client retention program. We take great pride in helping customers: Grow their Business, Improve their Closing Ratios and Enhance their Value.
We offer the most comprehensive customer service with 100% of our staff being FCRA certified. When you call, you will talk to a live person, we hate hold music as much as anyone and endeavor to make sure that a live person answers the phone.
Bottom Line…What’s Important To You, Is Important To Us!
**[Learn more →](https://www.advcredit.com/)**
the impact
Horrible Borrower Experience
Ever wonder why your Net Promoter Score (NPS) might take a sharp 50-point dive?
One reason could be the repeated requests for information your clients have already provided.
Over-collecting data may seem advantageous to your team, but it's a different story from your borrowers' perspective.
Discovering they've provided unnecessary information can be a source of annoyance and inconvenience.
These practices can strain the customer relationship.
**Is this really the way to treat the lifeblood of your business?**

---
Zero Differentiation from your Peers
Fact check: Most lenders' websites echo the same promises: a transparent process, the latest technology, and respect for the borrower.
**Same Loans, Different Lenders**
Given that most mortgage lenders offer similar loan programs, your differentiators narrow down to service, reputation, and rates/fees.
**Stuck with Outdated Systems**
But how can you truly distinguish yourself if you're operating on the same decades-old system as everyone else?
**What levers can you pull to stand out from the crowd?**
---
Check-the-Checker Workflow
Ever find yourself in a situation where half of your team's efforts are consumed by double-checking work already done by someone else?
**A Matter of Control**
Could it be because your current system offers limited control over how data is managed, leading to crucial information being overwritten?
**Complicated Systems, Confusing Tasks**
Or is it due to the complexity of your systems, causing people to forget the correct procedures — particularly when dealing with less common loans?
**The Power of Trust**
Imagine a scenario where everyone could trust that the work completed before them was accurate and thorough.
**Wouldn't that be a game-changer for efficiency and morale?**

---

Audit Nightmares
Unless you're a federally chartered bank — and let's not forget the unique compliance challenges there — every state in which you lend has an interest in scrutinizing your processes. They want to ensure you're not causing harm to their residents.
**Costly Consequences**
Errors in this high-stakes environment are more than just a nightmare — they can directly impact your bottom line.
**Auditors' Trust: Does Your System Measure Up?**
Does your current system instill confidence in auditors that every detail — every "i" dotted, every "t" crossed — is being meticulously handled in your process?
**Imagine having a system auditors know does the job... how much better would you sleep?**
## Our Philosophy
It is your data.
It is your business.
**We want to empower your success and not nickel-and-dime you to death.**
For example, your subscription does not include monthly minimums. The mortgage cycle is seasonal, and locking you into a monthly minimum number of loans means you either pay more per loan on months with lower volumes or overage charges when you are busier. Either way, you lose (and the vendor wins).
**We don't play that game.**
Instead, your subscription with Wilqo includes a targeted number of closed loans for the year (the more you commit to, the lower your per-closed-loan price). Then, each month's volume gets deducted from that target. If you run out of loans before the year is up, you just buy another bundle.
**Easy. Fair. Predictable.**
Wilqo isn't just better ... we're different.
Our Partners
[ ](https://www.asurity.com/)
[ ](https://docutech.com/)
[ ](https://www.factualdata.com/)
[ ](https://singlefamily.fanniemae.com/)
[ ](https://sf.freddiemac.com/)
[ ](https://www.loanpass.io/)
[ ](https://www.lodestarss.com/)
See More of Our Integration Partners
[ Click Here ](https://wilqo.com/integration-partner?hsLang=en)
[](https://wilqo.com/?hsLang=en)
The first unified Production Optimization Platform
built for the modern mortgage enterprise.
##### PLATFORM
- [POS / LOS](https://wilqo.com/pos-los)
- [Content Intelligence](https://wilqo.com/content-intelligence)
- [Business Intelligence](https://wilqo.com/business-intelligence)
##### COMPANY
- [The Wilqo Way](https://wilqo.com/wilqo-way)
- [Partners](https://wilqo.com/integration-partner)
- [Team](https://wilqo.com/team)
##### RESOURCES
- [Videos](https://wilqo.com/videos)
- Documentation
- Support
---
© 2026 WILQO, LLC. ALL RIGHTS RESERVED.
- [PRIVACY](https://wilqo.com/privacy-policy)

Founded by mortgage industry veterans, we are passionate about solving the problems that plague the industry.

Explore
- [About Our POP](https://wilqo.com/about-pop?hsLang=en)
- [Team](https://wilqo.com/team?hsLang=en)
- [Book A Demo](https://wilqo.com/moreinfo?hsLang=en)
- [Video Library](https://wilqo.com/videos?hsLang=en)
Follow Us
- [LinkedIn](https://www.linkedin.com/company/wilqo)
- [Youtube](https://www.youtube.com/channel/UCUOoYgJbuFXbxo4vtBPuIfQ)
Copyright © 2026 Wilqo LLC
[Privacy Policy](https://wilqo.com/privacy-policy?hsLang=en)
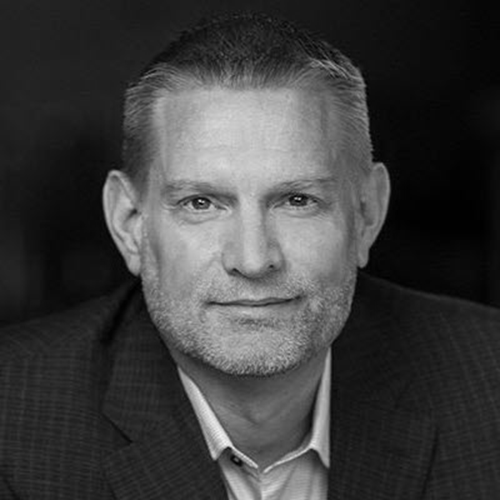
### Lance Reese
CEO
Lance Reese, Wilqo's CEO, boasts an illustrious 30-year journey, blending technology with operational excellence across global industries.
Prior to Wilqo, Lance skyrocketed sharperimage.com's growth by 150% during his tenure as CEO. He led Amerimark Interactive, a $500M direct-to-consumer retail giant, and donned key roles from board memberships to COO and CIO stints at diverse companies, one being Docutech.
A tech aficionado from youth, Lance launched a tech consultancy at 16, evolving it into a pioneering contract management software venture for nuclear waste management.
A proud graduate of Indiana University and Brigham Young University with degrees in business administration and mathematics, Lance's commendation at the Indiana Kelley School of Business Academy of Alumni Fellows in 2021 is testament to his dedication. He continues to nurture his connection with Kelley, offering MBA students insights via case study endeavors.
Orlando is home for Lance, where he cherishes moments with his family, including four children, their partners, and three grandchildren.
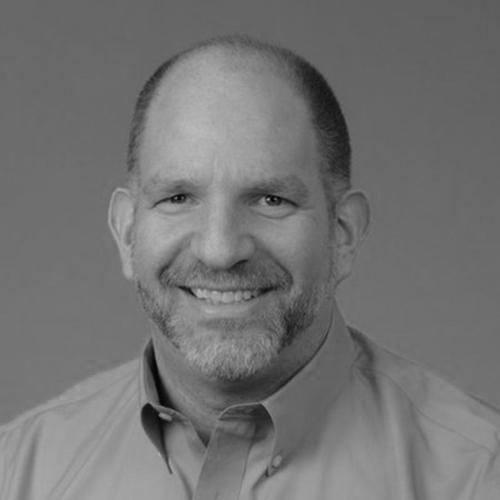
### Rob Katz
Chief Strategy Officer
(Co-Founder)
Rob Katz, Chief Strategy Officer at Wilqo, is an industry veteran leveraging automation, workflow optimization, and data analytics to revolutionize mortgage banking. He excels in simplifying complex tasks and using data for strategic decision-making.
Before co-founding Wilqo, Rob held high-ranking roles in various notable companies. He was an EVP at a highly successful regional internet company, where he drove up customer satisfaction while reducing operating costs and improving employee satisfaction.
After serving as CIO at Monument Mortgage, a publicly-traded national lender, Rob joined Datatrac, a prominent loan origination system, where he ultimately served as President and CEO before successfully selling the company to Ellie Mae. He then led the product team at Ellie Mae before joining ReverseVision, the leading provider of workflow automation for reverse mortgage lenders.
An alumnus of UCLA with a degree in Microbiology, Rob's analytical skills have been key in navigating the technicalities of the mortgage industry. Residing in Scottsdale, Arizona, Rob balances his busy career with family life. He's a proud father and has been married for 31 years.
### Kelli Hodges
Head of Operations
Introducing Kelli - Driving Innovation in Mortgage Lending
Kelli has a proven track record of leading enterprise-level initiatives at esteemed mortgage lending and technology firms. With two decades of experience in the industry, she remains committed to constant growth and learning, enabling her to oversee operations and identify opportunities across functional departments. Her insights foster business innovation and consistent growth.
Before joining Wilqo, Kelli served as COO for Mortgage Coach and Head of Operations at Optimal Blue. Her expertise earned her recognition, including the HousingWire Insiders award and National Mortgage Professional's Mortgage Lending's Women of Inspiration award.
Beyond her work, Kelli cherishes a healthy work-life balance. She enjoys sharing joyful moments with her family, friends, and beloved pets, embracing laughter and meaningful connections beyond the workplace.
Kelli's dedication and passion for building strong relationships drive her success at Wilqo as we reach new heights together.
### Gregg Holsapple
Head of Products
(Co-Founder)
Gregg's journey through the mortgage realm is both rich and extensive. His initial years saw him deep in the trenches with independent mortgage bankers, honing skills in secondary marketing, fulfillment, and systems integration.
Two decades back, Gregg transitioned into the tech heartbeat of the mortgage sector. He helmed product divisions for industry titans like DataTrac, Docutech, and ReverseVision. Then, with a burst of entrepreneurial spirit, co-founded Wilqo.
For Gregg, technology isn't just about innovation; it's a tool to refine and rejuvenate the lending process. His vision? A seamless experience for borrowers, coupled with peak efficiency for lenders.
Off-duty, Gregg's wanderlust takes him to far-off places, or he's simply unwinding with his beloved pups.
### Brian Perry
Head of Architecture
(Co-Founder)
Brian's professional journey has been exclusively woven through the fabric of mortgage technology.
After earning a degree in Integrated Science, Mathematics, and Computer Science from Northwestern, he leaped into a start-up revolutionizing the mortgage secondary market. His next move, to Optimal Blue, saw him ascend to the role of Chief Architect. His pivotal contributions there reshaped the mortgage landscape, standing out as one of the most transformative tech solutions in the industry.
Hearing of an opportunity to address challenges in the loan manufacturing process, Brian eagerly joined the team as a co-founder of Wilqo.
Apart from steering Wilqo's architectural vision, Brian is a board member for the Housing Navigator Massachusetts, a nonprofit championing affordable rental housing.
Off the grid, Brian savors quality time with his wife, and hiking and exploring nature's embrace.
### Kirk Reese
Head of Engineering
Earning a B.S. in Mathematics/Statistics from Brigham Young and an M.S. in Applied Mathematics from the University of Maryland, Kirk has always been inclined towards practical problem-solving. He's contributed across various industries from Defense to Mortgage and has a particular fondness for the vibrant challenges startups offer.
Despite exploring other sectors, the pull of the Mortgage industry has been irresistible. Kirk believes in attracting and tackling the best problems with the best teams. His philosophy? Embrace ownership, remain responsive, and savor the journey.
When Kirk steps away from engineering challenges, he treasures family time. A proud father and even prouder grandfather of seven, traveling to culinary-rich destinations is a favorite family pastime.
### Jodi Hall
Senior Industry Advisor
Jodi Hall, Senior Industry Advisor, is a thought leader not only in mortgage lending but in mortgage technology.
Before joining Wilqo, Jodi was an executive leader at two well know mortgage lenders who she joined at their infancy and helped them grow not only their productions, but also their culture and reputation. After climbing the ladder to COO at CrossCountry Mortgage, a now top 5 independent mortgage banker (IMB), Jodi served as the President and COO of Nationwide Mortgage Bankers. Jodi grew NMB from a small to a medium size IMB, obtained their Fannie, Freddie, and Ginnie seller servicer approvals, lead all companywide initiatives and built a culture unlike any other in the industry, in four short years.
Jodi is an active member of The Mortgage Collaborative, has served on The Chase Home Loan Advisory Board, and holds several mortgage industry advisory board seats with companies focusing on mortgage technology.
Residing on her horse farm in Cambridge, OH, with her wife Carol and her four-legged children, she supports the community that "built her". Her passion and perseverance came from the farms of Summerfield, Ohio and her alma mater Shenandoah who she proudly refers to as Zeps Nation.
Jodi's passion is to be an integral part of revolutionizing the mortgage industry and empowering the next generation of industry professionals to carry her passion for decades to come.
At Wilqo, Jodi will lead and support the organization in bringing her passions to life.
### Tom Morelli
Head of Data Analytics
Tom Morelli, Head of Data at Wilqo, is focused on maximizing value from existing mortgage data as well as rethinking how data enables the industry. His team’s process is understanding industry pain points, vetting all possible solutions, and presenting actionable options.
Tom joined Wilqo in 2021 after having built out reliable data practices at multiple companies. He worked with business leaders to challenge preconceived notions about their KPIs and align their teams on common goals.
An alumnus of Michigan State University with a degree in Finance, and a Masters Degree in Project Management from Walsh College, Tom got his start in the insurance industry leading numerous successful process improvement initiatives. His background covered compliance, quality, reducing cycle times, and identifying opportunities to increase revenue generation.
Tom currently resides in Camarillo, California with his wife Hannah of four years and two year old daughter, Eleanor.
Never one to be satisfied with a status quo in life, Tom and his team are always looking for new ways for data to bring value to Wilqo and the industry.
### Annette Wolf
Head of People & Culture
Annette Wolf, Head of People and Culture, joined Wilqo in November 2021. Annette is passionate about the impact people and culture can make to the success of a company.
During her 20-year career, she has focused on creating and supporting dynamic, high performing technology driven organizations. Most recently she led Human Resources for Optimal Blue where she helped grow the organization from 90 to more than 250 employees while fostering a culture of innovation and collaboration.
Annette grew up in Houston, Texas, but headed to the Northeast for her undergraduate studies. She received her bachelor’s degree in mathematics and economics from Boston University. After 4 winters in the Northeast, Annette was happy to return to Texas for her graduate studies. She received her MBA from The University of Texas at Austin with a focus on Entrepreneurship and Human Resources.
Annette currently lives in the Dallas/Fort Worth area with her husband and son. Outside of her work with Wilqo, Annette enjoys spending time with her family, particularly if it includes any type of Disney-related travel.
### Ty Jenkins
Chairman
(Co-Founder)
Ty Jenkins isn't just an entrepreneur; he's a trailblazer determined to revolutionize the industries he delves into. As the visionary founder and former CEO of Docutech, he pioneered dynamically generated collateral instruments for the mortgage sector. His hands-on work with every loan origination software (LOS) system laid the foundation for three critical realizations:
1. LOSs weren’t crafted for full-fledged integrations.
2. A majority of lenders are disillusioned with their LOS.
3. Changing an LOS? That's a notion they dread even more.
In 2020, after transitioning his stake in Docutech to First American, Ty embarked on a new mission: addressing the prevalent challenges of mortgage bankers. Leveraging insights from the Fintech realm and rallying a team of seasoned professionals he'd collaborated with throughout his journey, Wilqo was born.
Beyond business, Ty is an authentic cowboy at heart. You might spot him wrangling cattle on his Wyoming ranch or globetrotting with his beloved wife. Family time remains his cherished retreat, especially with his children and grandchildren.
### Larry Huff
Director
(Co-Founder)
Larry Huff co-founded and was Co-CEO of Plano, Texas-based Optimal Blue, LLC, a cloud-based provider of pricing, secondary marketing, and other content-enabled enterprise lending services, including compliance, consumer direct and point-of-sale technology for the financial services industry. Larry, who has an extensive record of success in the mortgage, leasing, and technology sectors, co-founded Optimal Blue with Dr. Ivan Darius. He has over 20 years of executive experience in technology, business, and product development and operations.
In his current position, he shares responsibility for the company's day-to-day management, emphasizing corporate strategy, sales and marketing, and business development. Larry left Optimal Blue as part of the company's successful sale to GTCR, a Chicago-based private equity firm, in July 2016. Since leaving Optimal Blue, Larry is now an independent board member on four SaaS companies' Board of Directors.
Before co-founding Optimal Blue, Larry was Chief Operating Officer and Co-Founder of Sollen Technologies, LLC, the first-ever cloud-based product and pricing engine for mortgage bankers. Earlier in his career, Larry worked for the Oakwood Group, a London-based Private Equity firm, and founded and managed a large mortgage brokerage and banking firm in Dallas, Texas.
Larry earned two Bachelor of Science degrees in Geology and Civil Engineering from Texas A&M University.
### Ivan Darius, Ph.D.
Director
(Co-Founder)
Ivan H. Darius, Ph.D., co-founded Plano, Texas-based Optimal Blue, the leading SaaS provider of product eligibility and pricing engine (PPE) technology and content management in 2002. Ivan co-founded Optimal Blue with Larry Huff, bringing more than 30 years of executive experience in technology, product development, and operations.
While Co-CEO of Optimal Blue, he was responsible for managing the day-to-day activities of the company as well as focusing on the technical and strategic product direction. He designed the Optimal Blue system to leverage the convergence of technology with content management to seamlessly connect investors, lenders, and originators to more efficiently source, manage, price, and lock a loan in real-time.
Before founding Optimal Blue, Ivan was president and CEO of Sollen Technologies LLC (1999-2002) in Dallas. While there, Sollen became the first successful ASP selling automation and process improvement tools to the mortgage industry. Additionally, he designed and implemented the first highly scalable, massively parallel decision engine for pricing and eligibility. The company grew from zero to $2.5 million in annual revenue during his tenure.
Ivan’s career started at Texas Instruments Incorporated (1980 – 1993). His responsibilities as Director of the Decision Systems Lab included the application of artificial intelligence (AI), simulation-based modeling, and science-based operational improvement techniques to the semiconductor manufacturing process.
Ivan attended The Catholic University of Leuven, Belgium, where he earned a Bachelor of Science in physics, summa cum laude and a Ph.D. in Physics, magna cum laude. He is fluent in English, French, Dutch, and has a working knowledge of German.
When he is not thinking of new ways to improve efficiency in the mortgage origination process, Ivan enjoys time with his 4 grandchildren and the occasional game of golf.
### Jeff Benjamin
Director
(Co-Founder)
With four decades of experience in housing finance and mortgage technology, Jeff Benjamin has a lot of experience with the ebb and flow of lending cycles. Right out of college he joined a Phoenix-based Independent Mortgage Banker where he quickly became the top retail originator. Bank of America then purchased the IMB and tasked Jeff with running their third-party lending initiatives in the Western US. He continued in the role running both wholesale and correspondent sales until 1990. He left the bank a few weeks before getting married in 1990 and set off with his new bride to spend nearly a year exploring the US and Canada on a motorcycle. When he returned to the working world, he joined then-regional technology and compliance provider, Desert Document Services, and led their highly successful efforts to go nationwide over the next several years. Jeff then joined Ellie Mae in 2001, eventually ascending to the role of SVP of Sales and Client Management. With the company on a run rate to hit a billion in revenue, he took a bow in early 2020, right on the cusp of the global pandemic.
Now a vital part of Wilqo's leadership, Jeff harnesses his rich experience to champion the transformative potential of our Production Optimization Platform within the industry. Away from the boardroom, he spends time in his beloved Colorado mountain biking, snowboarding, motorcycling and searching out new craft cocktail experiences. Jeff and his wife especially enjoy taking their RV around the country most any time, but especially to see college football games during the Fall.
## The cost to produce a loan isn't sustainable
The Mortgage Bankers Association reports an alarming trend: lenders spend an average of $13,000 to close a mortgage, with costs rising each quarter.
About half goes to the loan officer, with a large part of the rest wasted on loans that never close, or correcting errors that get caught by your investors.
Your expenses are hitting profitability hard.
It's evident - the traditional lending model is flawed.
**Charlie reduces the cost to produce a loan.**
[ Request a Demo ](https://wilqo.com?hsLang=en#contact-us)
## Consumers do NOT enjoy the borrowing process
Who thinks getting a mortgage is easy?
The document gathering and real-time status tracking — it's a pain for borrowers and Loan Officers.
Of all purchasing experiences today, mortgages are the most stressful, demanding a more simplified, efficient process.
**Charlie improves the borrower and Loan Officer experience.**
[ Request a Demo ](https://wilqo.com?hsLang=en#contact-us)
## No other white-collar industry faces our staffing issues
You are either over or understaffed 80% of the time!
This imbalance hurts morale and wastes resources on short-term hires' training.
This hiring-firing cycle (the "yo-yo effect") is frustrating and only benefits the recruiters collecting placement fees.
Staffing is widely considered the industry's biggest challenge (after rate increases).
**Charlie solves the staffing yo-yo problem.**
[ Request a Demo ](https://wilqo.com?hsLang=en#contact-us)
## You can get nearly anything with 1-click ... except a mortgage
Order something online? Enjoy it the same-day delivery.
Walk into a car dealership? Drive home in your new vehicle.
But apply for a mortgage? Brace yourself for several weeks of waiting — if you're lucky.
Why does the mortgage process feel like we're stuck in the '80s?
**Charlie optimizes the loan manufacturing process and speeds up the lending lifecycle.**
[ Request a Demo ](https://wilqo.com?hsLang=en#contact-us)
### Jeff McKay
Sr Account Executive
Jeff McKay is a Senior Account Executive for new sales at Wilqo.
His nearly 30-years in mortgage banking includes:
- Loan Officer
- Managing secondary for retail and wholesale IMBs (including processing/underwriting scratch-and-dent loans)
- LOS administrator
- Managing the developers and help desk support staff for H&R Block Mortgage
- 6 years as a wholesale account executive (including underwriting loans in the field)
- 6 years with AllRegs
- 6 years with ICE/EllieMae on the Encompass sales team
Jeff graduated from Western Oregon State University with a business and military science degree, earning him a commission in the US Army where he served for over 7 years.
Jeff lives in Raleigh NC with his wife and 3 children. He enjoys time in his garden, working in his wood shop, competitively shooting, hunting, and ocean fishing.

### John Haring
Head of Compliance
John Haring serves as the Head of Compliance for Wilqo.
With over 20 years of experience in regulatory compliance and software development, John is responsible for ensuring that Charlie® brought to you by Wilqo, provides clients with the solutions they need to stay compliant with complex and ever-changing regulatory requirements.
Prior to joining Wiqo, he served as the Senior Director, Product Management at ICE (formerly Ellie Mae), where he spent the better part of 12 years supporting banks, lenders and brokers in implementing significant regulatory changes that impact the mortgage industry.
In 2015 Haring was named one of HousingWire’s Rising Stars in recognition for his accomplishments in helping the industry prepare for implementing “Know Before You Owe”.